

Top Software Companies in Denver & Boulder, CO (1,322)
.png)
We bridge deep tech into farming and ranching. Halter enables farmers and ranchers to remotely shift, virtually fence and proactively monitor their cows’ health and behavior. Can you imagine watching 500 cows or cattle walk calmly towards the milking shed or their next break? No quad bikes, no dogs, no fences. Just a herd of cows walking at their own...

Halter's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue at the New Zealand entity rose to NZ$98.1m for the nine months to December 2025 versus NZ$71m for the prior 12-month period, and farms served reportedly increased from 2,000 to 3,500 alongside collars deployed growing from 500k to 1.5m. Feedback suggests headcount more than doubled within 12 months, indicating scaling operations to support demand.
Investor Backing & Capital Strength: A US$220 million Series E at a reported US$2 billion valuation and a prior US$1 billion valuation signal substantial capacity to fund expansion, product development, and market entry. Feedback suggests plans to hire 200+ roles and expand into the UK and Ireland, supported by this capital base.
Market Expansion: Operations reportedly extended rapidly in the United States with approximately 1,000 ranch customers and activity in more than half of US states. Feedback suggests international expansion plans into Europe and increased satellite-collar deployments are opening new, harder-to-serve markets.
Legora is the agentic operating system for legal work, supporting lawyers in research, review, and drafting across complex matters. It is used by more than 130,000 legal professionals at more than 2,000 leading law firms and in-house legal teams across over 80 markets.

Legora's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue momentum is reflected in ARR rising from $100 million to over $200 million within roughly six months after an under-18-month climb to the first $100 million.
Investor Backing & Capital Strength: Recent financing includes a $550 million Series E at an $8.8 billion valuation, a sharp step-up from earlier 2026 rounds. This signals ample resources to fund continued expansion.
Market Expansion: Operations span 80+ markets with the United States becoming the largest revenue market and more than half of AmLaw 50 firms as customers. Headcount surpassed 1,000 across 18 offices, supporting international scaling.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales are rising to record levels at the group level, and the U.S. business reports multibillion-dollar annual sales. Management guidance points to further sales increases, supported by continued demand across defense and aerospace programs.
Resilient & Sustainable Growth: A record order backlog provides multi-year visibility into future work and delivery schedules. Continued order intake and long-duration defense programs bolster confidence in sustained activity.
Market Expansion: Significant U.S. facility investments—such as the Jacksonville shipyard upgrade and added capacity in Louisville—expand manufacturing and repair capabilities. Added capacity is aimed at supporting U.S. Navy work, submarine construction support, and other defense production needs.

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent financials show accelerating top-line expansion, with quarterly revenue surpassing the billion-dollar mark and full-year results climbing meaningfully. Momentum continued into 2026, reflecting broad demand across observability, security, and AI-related offerings.
Healthy Cash Flow: Operations are generating substantial operating and free cash flow alongside growth. This pattern persisted through mid-2026, indicating efficient scaling.
Strong Market Position & Advantage: Industry evaluations repeatedly place the company as a Leader in observability and digital experience monitoring, including top positioning for execution. Recognition such as Customers’ Choice and multi-product leadership suggests deep adoption and competitive strength.
Cat Digital is the digital and technology arm of Caterpillar Inc., responsible for bringing digital capabilities to our world-famous yellow iron. With over 1.5M connected assets worldwide, our teams use data, technology, advanced analytics and AI capabilities to help solve our customers' toughest challenges.
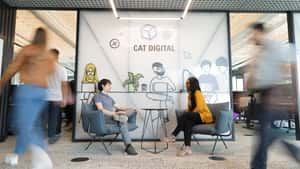
Caterpillar's Top Stability & Growth Strengths
Strong Revenue Growth: Sales and revenues increased 24% year over year to $20.5 billion in Q2 2026, with the first half of 2026 up 23% versus the prior year. Full-year 2025 also reached a record $67.6 billion, indicating momentum that accelerated into 2026.
Profitability: Operating profit margin improved from 17.3% to 20.9% in Q2 2026 and profit per share climbed sharply, supported by higher volumes and favorable pricing. These signs point to stronger earnings conversion alongside top-line growth.
Future-Ready Strategy: A backlog surpassing $72 billion, rising orders tied to data‑center power demand, and a planned ~$1 billion North Carolina capacity expansion signal preparation for sustained demand. Management also raised its 2026 sales-growth outlook to the mid- to high-teens.
As the AI platform for business transformation, we're putting AI to work across organizations — freeing people for work that matters. Making old tech work with new tech. Reaching across departments, from the front office to the back office and every office in between. Our ambition? To become the AI defining enterprise software company of the 21st century (or "AI...
ServiceNow's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as rising at a strong, double‑digit pace across recent quarters and years, with subscription sales increasing alongside total revenue. Company guidance for subscription revenue was raised, reinforcing the momentum.
Resilient & Sustainable Growth: Remaining performance obligations and current contracted revenue expanded, indicating meaningful visibility into future sales. Growth in large enterprise customers and multi‑million‑dollar deals further supports durability.
Innovation-Driven Growth: AI offerings became a meaningful commercial driver as ServiceNow AI exceeded $1 billion in annual contract value and deployments accelerated. Adoption of workflow and AI products is highlighted as a primary catalyst.

Engine is the AI-native platform for intelligent travel. For a decade, Engine has built the proprietary technology and supply behind modern business travel, serving 40,000 customers and 2 million travelers, along with leading travel and AI companies that build on Engine's infrastructure. One system powers business travel, group travel, human agents, and AI agents. Engine was named TravelTech’s Reservation Platform of...

Engine's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is described as growing sharply year over year in 2024, with profitability reported at that time. This provides evidence of commercial momentum beyond user or customer counts.
Investor Backing & Capital Strength: Capital resources are reinforced by a sizable Series C led by a major investor at an increased valuation relative to 2021. This level of funding signals capacity to invest in scaling operations and product.
Market Expansion: Expansion includes the addition of flights and rental cars, acquisitions aimed at managed corporate travel, and a 2026 technology partnership with Navan. These moves broaden distribution and customer reach beyond the original hotel-booking focus.
KPA solutions help clients identify, remedy, and prevent workplace safety and compliance problems across their entire enterprise. The combination of KPA’s easy-to-use software platforms, consulting services, and award-winning training content helps organizations minimize risk so they can focus on what’s important—their core business. For nearly 40 years, KPA has helped 10,000+ clients achieve regulatory compliance, protect their business, and keep...

KPA's Top Stability & Growth Strengths
Strong Market Position & Advantage: KPA reports serving 40 of the top 50 U.S. dealership groups and more than 15,000 client locations, indicating deep penetration in its automotive niche. The 2026 refocus on automotive is intended to deliver more specialized products and dedicated support for these customers.
Product Line Growth: Recent launches include AI-powered lead-response audits, performance dashboards, advertising archives, and new certification programs. Acquisitions such as ComplyNet, AnchoRock, and iScout have broadened capabilities across dealership compliance and construction safety.
Investor Backing & Capital Strength: Providence Equity Partners lists KPA as an active portfolio company and documents the 2026 business separation. Private-equity ownership provides resources for continued investment and restructuring, even though it does not itself prove revenue growth.
Vendavo partners with the world’s leading companies to accelerate growth and profitability, advance innovation, and build more prosperous communities. Our powerful, cloud-based, AI-powered pricing, selling, and prescribing solutions empower global manufacturers and distributors to manage, optimize, and digitize their end-to-end commercial processes. But we offer so much more than software. Our proven, repeatable process, and passionate, experienced people accelerate value...

Vendavo's Top Stability & Growth Strengths
Strong Revenue Growth: Annual recurring revenue increased 12% in 2023, alongside 43% growth in higher-margin recurring services. While historical, these figures indicate expansion in the recurring business model.
Innovation-Driven Growth: Vendavo AI was launched in 2025 with further AI and machine-learning enhancements announced in 2026, embedding intelligence across pricing, quoting, and rebate workflows. These investments point to continued product development intended to expand the platform’s value.
Market Expansion: In July 2026 the company announced an agreement to acquire Model N’s High-Tech business unit and introduced a High-Tech Revenue Management solution targeting semiconductor and high-tech manufacturing. These moves suggest efforts to broaden industry reach through acquisitions and new offerings.

Accuris gives engineers trusted answers, not just access. Our Engineering Intelligence platform combines verified data, actionable insights, and purpose-built workflows — so technical and business leaders can move faster, reduce risk, and make decisions they can defend.

Accuris's Top Stability & Growth Strengths
Strong Revenue Growth: Management reported substantially accelerated revenue growth in 2024 and being on track to exceed financial targets, although specific figures were not disclosed. This indicates positive commercial momentum in its first year operating independently.
Product Line Growth: Recent launches—including Accuris Thread, an AI Assistant, BOM Intelligence, new Engineering Intelligence tiers, and Accuris Connect—extend coverage from standards into requirements, AI research, and supply-chain workflows. These additions broaden the portfolio and create more avenues to serve existing and adjacent use cases.
Market Expansion: Company communications describe more than 1,000 employees across 20 countries, a new Denver headquarters, and expanded offices in the UK, India, Malaysia, and Japan. This signals a wider geographic presence and scaling operations.
At Gloo, we believe relationships catalyze growth, and when technology serves relationships, the world can change, one life at a time. So we’re building the technology platform for the faith ecosystem, so people can flourish and communities can thrive. We serve those who serve. From pastors and publishers, developers and donors, individuals and beyond—our technology platform releases the collective strength of...

Gloo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported to have surged at triple-digit rates year over year across consecutive quarters, with full-year guidance raised to $200 million. Growth is noted as continuing into the latest reported quarter rather than relying on older periods.
Market Expansion: Customer reach is broadening with more than 30 $1M+ ACV customers (including the first above $10M) and over 40 universities served. Acquisitions and larger enterprise relationships are cited as expanding commercial footprint across adjacent segments.
Innovation-Driven Growth: Expansion into AI and integrated services (e.g., Gloo 360 and AI offerings) is associated with subscription growth. Added capabilities from deals like Igniter and Masterworks are presented as reinforcing product momentum.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising steadily, including 11% year-over-year growth to $192.8 million in Q2 2026 and 7% growth for full-year 2025. The step-up from 6% growth in Q1 2026 to 11% in Q2 indicates accelerating momentum.
Profitability: Adjusted EBITDA increased 30% year over year in Q2 2026 as margin expanded from 34% to 37%, signaling operating leverage. Net income also improved to $19.4 million from $11.1 million year over year in that quarter.
Healthy Cash Flow: Guidance points to free-cash-flow growth in the high-40% range for 2026 alongside adjusted EBITDA growth of more than 20%. Operating cash flow reached $57.4 million in Q2 2026.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Strong Revenue Growth: Square’s segment revenue increased 10% in 2025 and rose 16% year over year in Q2 2026, pointing to renewed topline momentum. These gains accompany rising seller activity and broader ecosystem adoption.
Profitability: Gross profit reached about $1.16 billion in Q2 2026, up 13% year over year, after a 9% increase for full-year 2025. The trend indicates improving economic contribution from processing, software, and financial services.
Market Expansion: International GPV grew 28% year over year in Q2 2026 while U.S. GPV rose 10%, alongside traction with larger merchants and vertical solutions such as restaurants and banking. These patterns suggest widening geographic and segment reach.
We’re one of the world’s leading online gambling companies, revolutionizing the industry since 2000. Founded by Denise Coates CBE, we now employ over 10,000 people and serve over 120 million customers in 26 languages. We empower our employees to push boundaries and explore new ideas, cultivating a culture that celebrates and rewards creativity. This offers employees a wealth of...

bet365's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased by 9% to about £4.04 billion in the 52 weeks to March 2025. This points to continued top-line expansion despite heavier spending tied to new markets.
Market Expansion: A U.S. headquarters opened in Denver with plans for hundreds of roles and further state launches, alongside international entries in Brazil, Peru, and Serbia. The purchase of the Denver property for roughly $135 million underscores commitment to North American growth.
Strong Hiring & Retention: Average headcount rose from 6,085 in 2022 to 9,462 in 2025, and roles continue to be advertised across technology, trading, marketing, and customer service. Company materials cite a workforce of over 10,000, indicating substantial organizational scale.
For too long, child care programs have been stuck with clunky tools and manual processes, falling behind while other industries get all the high-tech toys. Playground is flipping the script. Playground is a proven platform for child care providers to streamline their operations, reclaim their time, and get back to the joy of teaching and caring. Our all-in-one child care management...

Playground (tryplayground.com)'s Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests ARR reportedly doubled year over year and was expected to at least double again, signaling rapid top-line momentum. While company-reported rather than audited, this is the clearest quantitative indicator provided.
Strong Market Position & Advantage: Feedback suggests adoption across more than 5,000 childcare programs and nationwide reach indicate meaningful scale and positioning. The September 2026 acquisition by Procare further underscores strategic relevance within the category.
Innovation-Driven Growth: Feedback suggests expansion from communications into billing, payroll, enrollment, reporting, subsidy management, and AI tools is broadening the platform’s value proposition. Frequent releases and a childcare-focused AI assistant point to ongoing product-led growth.
We believe insurance is about relationships. And technology should only make them stronger. We exist to empower independent agents, carriers, and MGAs. To drive their success. Because their success is our success. And their ambitions for tomorrow are our goals for today. Since our inception, we’ve been the technology backbone of the insurance industry. We began punching cards for independent agents over...
Vertafore's Top Stability & Growth Strengths
Strong Market Position & Advantage: Reported reach spans most top agencies and carriers and a large share of fast-growing MGAs, alongside a large professional user base and substantial annual transaction volumes. This entrenched footprint gives Vertafore a sizable installed base to deepen adoption and expansion across its core markets.
Innovation-Driven Growth: Continued AI investment is evident through the Velocity AI platform, multiple 2026 agent launches, and a Digital Underwriter vision targeting MGA workflows. These initiatives extend automation across policy intake, checking, submissions, reconciliation, and coaching, supporting expansion within existing accounts.
Investor Backing & Capital Strength: Ownership by Roper Technologies provides long-term capital support, with parent-company commentary highlighting continued ARR expansion across agency, MGA, and carrier businesses. This backing underwrites ongoing product development and strategic investment in cloud, data, and AI.
.png)
American medicine is the best in the world. But the American healthcare system is challenged by high administrative costs that burden patients, health systems, and insurance companies with unnecessary expenses. We are focused on addressing those challenges. We use GenAI to improve the most pressing financial pain points in the revenue cycle. We’re one of the first companies to deploy GenAI...
AKASA's Top Stability & Growth Strengths
Strong Revenue Growth: Feedback suggests AKASA reports more than tenfold growth since mid-2024 and nearly sixfold year-over-year inpatient volume processed, indicating rapid commercial traction and usage expansion.
Market Expansion: Feedback suggests deployments have broadened across major U.S. health systems, with a footprint reportedly spanning roughly 500 hospitals and customers representing about 10% of U.S. inpatient discharges.
Investor Backing & Capital Strength: Feedback suggests AKASA has attracted substantial capital, with reported total funding around $200M+, providing resources to scale products and partnerships.
Dynatrace lets customers understand their business like never before, so they can see beyond the complexity, find and fix problems faster and automate manual tasks with Al — so they can focus on what truly matters: running their business.

Dynatrace's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is advancing at double-digit rates across multiple periods, with FY2026 revenue rising 19% to about $2.02B and fiscal Q1 FY2027 revenue up 16% to $555M. ARR also increased 17% in the latest quarter, reinforcing breadth of growth in a subscription model.
Healthy Cash Flow: Cash generation is robust, including approximately $529M in free cash flow for FY2026 and operating cash flow of roughly $306M in Q1 FY2027. These indicators suggest expansion is supported by solid liquidity rather than heavy cash burn.
Product Line Growth: Log management is scaling rapidly, with annualized consumption reaching about $200M in Q1 FY2027 and growing at more than 100% year over year. Investment in AI-powered operations and platform capabilities is extending the growth runway.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Quarterly revenue increased materially year over year in Q2 2026, and full-year 2025 sales also rose. The acceleration into 2026 alongside expanding user metrics signals momentum in top-line performance.
Healthy Cash Flow: Free cash flow turned positive and expanded meaningfully versus the prior year, alongside a large step-up in adjusted EBITDA. This points to improving cash generation and operating efficiency.
Diversified Revenue Streams: Subscriptions and other direct revenue grew much faster than advertising, with products like Snapchat+, Lens+, and Memories contributing significantly. This diversification reduces sole dependence on the ad cycle and broadens monetization levers.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Healthy Cash Flow: Cash generation is described as substantial, with unlevered free cash flow of about $1.016B in 2025 and $283.5M in Q2 2026, indicating strong cash-producing ability despite modest top-line growth.
Profitability: Margins are portrayed as strong, with a 40.6% non-GAAP operating margin in 2025 and near 40% in Q2 2026, reflecting disciplined cost management and efficient operations.
Resilient & Sustainable Growth: Feedback suggests core revenue excluding FormSwift has returned to slight year-over-year growth and paying users have increased for several consecutive quarters, pointing to stabilization and incremental expansion.



