

Top Tech Companies in Denver & Boulder, CO (5,944)
Legora is the agentic operating system for legal work, supporting lawyers in research, review, and drafting across complex matters. It is used by more than 130,000 legal professionals at more than 2,000 leading law firms and in-house legal teams across over 80 markets.

Legora's Top Stability & Growth Strengths
Strong Revenue Growth: Reporting indicates ARR accelerated from tens of millions in 2025 to $100M+ by April 2026, with subsequent coverage citing further gains (e.g., ~$150M–$200M). This pace is repeatedly described as the clearest signal of substantial commercial momentum.
Market Expansion: Disclosures describe expansion from ~20 markets in 2025 to 40–50+ markets by 2026, with new offices across hubs including New York, Denver, Sydney, Bengaluru, Chicago, and Houston. Customer counts rose from ~250 to 800, 1,200+, and 1,480+ over 2025–26 alongside this footprint growth.
Investor Backing & Capital Strength: Financing progressed from an $80M Series B at a $675M valuation to a $550M+ Series D and extension around $5.6B within a year. This indicates strong access to capital and investor conviction to fund rapid scaling.
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
Moov is a payments infrastructure platform making it easy to accept, store, send, and spend money all from a single, elegantly-designed API. Instead of stitching together multiple vendors, software companies simply add Moov to their products to get the latest in payment technology, user onboarding, licensing, compliance, and more.
Moov's Top Stability & Growth Strengths
Product Line Growth: Current materials show support for accepting payments, bank payments, wallets, issuing cards, payouts, account verification, and multiple rails including ACH, RTP, and FedNow, positioning the company as infrastructure rather than only a card processor. This broader workflow coverage can increase payment volume per customer and create more acquisition opportunities.
Strategic Partnerships: Recent announcements and legal documents reference collaborations with institutions such as Jack Henry, Visa Direct, Coinbase, SouthState Bank, and Veridian Credit Union. These relationships extend distribution into community and regional financial institutions and reinforce enterprise readiness.
Investor Backing & Capital Strength: The funding trajectory progressed from a $5.5M seed and $27M Series A in 2020 to a $45M Series B in 2023 led by Commerce Ventures with participation from Andreessen Horowitz, Bain Capital Ventures, and Visa. This pattern signals sustained access to capital aligned with scaling the business and infrastructure.
Welcome to Comcast. From the connectivity and platforms we provide to the content and experiences we create, we bring people together, globally. Our people think the world of our work, and that’s why our work is the best in the world.

Comcast's Top Stability & Growth Strengths
Healthy Cash Flow: Operating cash flow increased from $27.7 billion in 2024 to $33.6 billion in 2025, and Q2 2026 free cash flow was $4.6 billion, up 2.3% year over year. This indicates strong cash generation despite uneven top-line trends.
Diversified Revenue Streams: Connectivity revenue rose 4.2% to $46.0 billion in 2025 alongside growth in business services (to $10.2 billion), wireless lines (to 9.3 million), Peacock (revenue up 10% to $5.4 billion; paid subs up 22% to 44 million), and parks. Comcast also highlights six growth drivers—broadband, wireless, business services, studios, streaming, and parks—that represented about 60% of 2025 revenue.
Product Line Growth: Wireless and streaming scaled meaningfully, with approximately 1.5 million wireless line additions in 2025 and Peacock reaching 44 million paid subscribers that year and achieving first-time quarterly profitability in Q2 2026. Business services connectivity also expanded in 2026, including Q2 revenue up 3.7% and EBITDA up 5.0%.
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...
SRAM, LLC's Top Stability & Growth Strengths
Market Expansion: Facility build-outs in Portugal and new regional hubs in Italy, along with expansion in Taiwan and a Chicago HQ redevelopment, indicate a scaling global footprint. Company materials also cite 20+ locations across 10+ countries, underscoring broad geographic reach.
Product Line Growth: Recent launches such as RED AXS (2024) and Force AXS (2025), coupled with acquisitions including Ochain, Hammerhead, TIME, and Velocio, expand coverage across drivetrains, electronics, and accessories. This cadence points to continued investment in portfolio breadth.
Strong Market Position & Advantage: The company is repeatedly characterized as one of the world’s largest bicycle-component manufacturers and a primary rival to Shimano across premium segments. This standing reflects deep relevance with OEMs and the aftermarket.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...
Square's Top Stability & Growth Strengths
Profitability: Square gross profit increased year over year in 2025 and again in recent quarters, with gains driven by processing, software, and financial solutions like Square Loans. Filings indicate this momentum continued into 2026, with growth excluding hardware also improving.
Strong Market Position & Advantage: Square is described as a leader in small-business POS and commerce, serving millions of sellers and processing a very large volume of payments. Industry recognition and scale suggest durable competitive positioning in its core segments.
Market Expansion: International payment volume is growing faster than the U.S., and sectors such as food and beverage led recent gains. Seller acquisition accelerated late in 2025, indicating widening reach across geographies and customer segments.

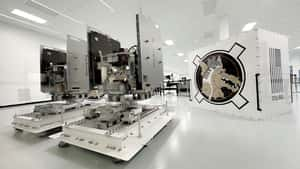
Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...
True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.
Hi. We’re Trustpilot. Trustpilot began in 2007 with a simple yet powerful idea that is more relevant today than ever — to be the universal symbol of trust, bringing consumers and businesses together through reviews. Trustpilot is open, independent, and impartial — we help consumers make the right choices and businesses to build trust, grow and improve. Today, we have more than 300...
Trustpilot's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose from $210.7M in 2024 to $261.1M in 2025 (+24% reported), with H1 2026 up 19% in constant currency to $151.4M. Consistent multi‑year increases and rising bookings (about +18% constant currency in FY2025 and H1 2026) indicate durable top‑line momentum.
Profitability: Adjusted EBITDA increased 69% to $40.7M in 2025 and rose 46% to $26.3M in H1 2026, expanding margins into the mid‑teens. Adjusted free cash flow also strengthened, reaching roughly $46.6M in 2025.
Market Expansion: North America is described as a fast‑growing region (bookings +27%), while enterprise traction accelerated (new logos +41% and >$20k customers compounding ~36% over three years). Platform scale expanded from 361M active reviews in 2025 to about 394M by mid‑2026, supporting broader commercial reach.
For too long, child care programs have been stuck with clunky tools and manual processes, falling behind while other industries get all the high-tech toys. Playground is flipping the script. Playground is a proven platform for child care providers to streamline their operations, reclaim their time, and get back to the joy of teaching and caring. Our all-in-one child care management...

Playground (tryplayground.com)'s Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have doubled over the prior year and to be on track for at least another doubling, with profitability cited before the Series A. Hiring alongside revenue growth is described, reinforcing momentum.
Product Line Growth: The platform has expanded beyond basic communications into billing, payroll, enrollment, reporting, subsidy management, and AI tools such as Camber. Current product pages reflect a substantially broader offering than the original scope.
Market Expansion: The company states it serves 5,000+ childcare programs and 500,000+ owners, directors, teachers, and families across all 50 states, and a September 2026 acquisition by Procare underscores expanded reach within the category. Earlier usage metrics and ongoing hiring further illustrate scaling activity.

.png)
American medicine is the best in the world. But the American healthcare system is challenged by high administrative costs that burden patients, health systems, and insurance companies with unnecessary expenses. We are focused on addressing those challenges. We use GenAI to improve the most pressing financial pain points in the revenue cycle. We’re one of the first companies to deploy GenAI...
AKASA's Top Stability & Growth Strengths
Strong Revenue Growth: Operating revenue increased meaningfully year over year while capacity also rose, signaling robust top-line momentum in tandem with expanding operations. Feedback suggests this growth has been sustained across consecutive fiscal periods.
Market Expansion: The network has broadened to 32 destinations with cumulative passengers surpassing 25 million, alongside added international routes and higher departures. These developments indicate widening reach and growing traffic throughput.
Future-Ready Strategy: Management outlines continued capacity growth over the next several years, supported by a large Boeing 737 MAX order pipeline. This long-horizon fleet plan underpins ongoing scale-up ambitions.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.
OmniCable is a premier redistributor of wire and cable, electrical products, and value-added services. OmniCable empowers our industry to be successful by providing an exceptional experience through operational excellence, accuracy and precision, and a partnership approach. With a multi-million dollar inventory and the acquisition of Houston Wire & Cable, we offer distributors products from the industry’s leading manufacturers. Since our...
OmniCable's Top Stability & Growth Strengths
Market Expansion: Additions of sales-agent coverage across Texas/Arkansas/Oklahoma, the Northeast/NYC/NJ, and the Mountain West in 2026, plus growth to 18 North American locations with larger facilities (e.g., a 285,000+ sq.-ft. Atlanta site, a 200,000-sq.-ft. Tampa site, and a new Mississauga branch), point to broader reach. The completed Kingwire acquisition adds eight warehouses and more than 625,000 sq. ft., further densifying the network.
Product Line Growth: A dedicated Communications Business Unit and expanded industrial automation/communications portfolio, combined with Kingwire’s strengths in aluminum, utility, data centers, and renewables, indicate a broadened offering. Approximately $400M of stated inventory supports availability across the enlarged SKU set.
Investor Backing & Capital Strength: Completion of the 2026 Kingwire acquisition alongside maintaining roughly $400M of inventory and major facility investments suggests access to capital to fund scale. Backing from Dot Family Holdings and prior acquisitions reinforce the platform’s capital support.

Luxury Presence is the leading growth platform for high-performing real estate agents, teams, and brokerages. The company provides agent-branded websites, advanced marketing tools, and AI CRM, the relationship engine powered by Presence AI that transforms an agent's sphere into a proactive source of new business. More than 18,000 real estate businesses rely on Luxury Presence to elevate their brand, attract...
Luxury Presence's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue milestones indicate ARR advanced from $75M+ in August 2025 to $100M by May–June 2026, alongside statements of over 40% revenue growth in 2025. These figures point to sustained top-line momentum over the period.
Market Expansion: The customer footprint grew from 87,000+ agents across 17,000+ businesses in early 2026 to 100,000+ agents across nearly 20,000 businesses by May–June 2026. This widening reach signals increasing platform adoption in its target market.
Innovation-Driven Growth: The launch of the unified Presence Platform and an AI-powered CRM, coupled with 300%+ growth in AI product and engineering teams since early 2025, underscores product-led expansion. Plans for $10M+ in AI infrastructure and faster release velocity further support an innovation-forward trajectory.

Together, we power advertising that enables billions of people to stay informed, entertained, and connected. We introduce them to new ideas, products, and services that make their lives better. And we help media owners of all sizes realize their full potential. That’s a lot — that’s the power of advertising. But it’s only possible with great technology. And that’s where Magnite...
Magnite's Top Stability & Growth Strengths
Profitability: Adjusted EBITDA and margins expanded, with Q2 2026 EBITDA up 30% year over year and margin improving to 37%, alongside higher net income. This pattern indicates operating leverage as earnings outpace the top line.
Strong Revenue Growth: Revenue rose 7% in 2025 and accelerated to 11% year over year in Q2 2026, with multiple sequential quarters showing improving trends. The recent trajectory points to faster growth rather than a flat profile.
Healthy Cash Flow: Free cash flow is guided to grow at more than 30% for 2026 and was later raised to the high-40% range, while Q2 2026 generated $57.4M in operating cash. Debt reduction in 1H 2026, including repayment of $205M in convertibles, further supports balance-sheet strength.
Apryse, previously known as PDFTron, takes document solutions to the next level, making work better and life simpler. As a global leader in document processing technology, Apryse gives developers, enterprise customers, and small businesses the tools they need to reach their document goals faster and easier. Apryse’s market-leading SDK drives digital transformation and powers next-generation software applications with dynamic document...
Apryse's Top Stability & Growth Strengths
Strong Revenue Growth: Reuters reporting indicates annual growth at a strong double-digit pace in 2025, aligning with sustained expansion activity. This growth is presented alongside ongoing platform and market advances from 2024–2026.
Profitability: EBITDA reportedly exceeded $100 million, indicating robust earnings capacity. This profile underpinned exploration of a multibillion-dollar sale process in 2025.
Product Line Growth: Acquisitions across 2024–2026 (e.g., LEAD Technologies, TallComponents, Scanbot SDK, Accusoft, PDF Tools AG) materially expanded capabilities in imaging, mobile capture, and high-performance PDF processing. Regular release cadences and AI-driven features further signal continued product expansion.
Ibotta (NYSE: IBTA) is a leading performance marketing platform allowing brands to deliver digital promotions to over 200 million consumers through a network of publishers called the Ibotta Performance Network (IPN). The IPN allows marketers to influence what people buy, and where and how often they shop – all while paying only when their campaigns directly result in a sale....
Ibotta's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with major platforms and retailers are expanding distribution and activity. Feedback suggests Uber and Giant Eagle joined in 2026 and a multi‑year 7‑Eleven deal was announced, while relationships with Walmart, Instacart and DoorDash underpin third‑party publisher redemption revenue up 27% year over year in Q2 2026.
Market Expansion: Network usage is scaling across publishers and channels. Feedback suggests Q2 2026 redeemers rose 21% to 20.9M, third‑party publisher redemptions increased 27% year over year, and H1 2026 total redemptions climbed from 163.3M to 179.4M.
Strong Market Position & Advantage: Positioning reflects a leading role in U.S. digital promotions with privileged retailer access. Feedback suggests Walmart exclusivity, a network reaching 200M+ consumers, and 900+ clients representing 3,100+ CPG brands provide a defensible competitive footing.
_0.png)
Red 6 is an innovative Augmented Reality (AR) technology startup leading the way in synthetic air combat training. Our primary technology, supporting our ATARS product, enables pilots to simulate the cognitive challenges of flying while accessing realistic, scalable training in dynamic outdoor environments

Red 6's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding has progressed from a $30M Series A (2021) to a $70M Series B (2023), alongside a $30M AFWERX STRATFI award matched by $30M in private funding and subsequent 2026 financing. These capital infusions indicate substantial runway to scale technology integration and delivery.
Strategic Partnerships: Partnerships with Boeing, Lockheed Martin, Northrop Grumman, Leonardo, and Sierra Nevada Corporation are documented, including SNC’s role supporting a $30M multi-MAJCOM Air Force contract. Such alliances embed Red 6’s systems across multiple OEM and service ecosystems, reinforcing market access.
Market Expansion: Activity has advanced from demonstrations to integrations across platforms including T-38, F-16, MC-130J, Apache, and M-346, with traction spanning the U.S. Air Force, U.S. Navy, and allies like the RAF. Federal obligations and new awards (e.g., STRATFI, SBIR Phase III task orders) point to widening adoption.
DigitalOcean is the Inference Cloud — a full-stack, production-ready cloud platform built to run AI applications with predictable performance, sustainable economics, and radically simpler operations at scale. We are built for teams turning AI into real products — not just training models. Our advantage is not fewer features, but fewer failure modes when operating AI at scale — combining minimal...

DigitalOcean's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported up 29% year over year in Q2 2026 to $281M, with ARR at $1.125B also up 29%. Guidance for 2026 was raised to about 30–31% growth alongside record incremental ARR and a sharply higher RPO.
Innovation-Driven Growth: AI-related momentum is pronounced, with AI customer ARR at $234M, up about 212% year over year, and the launch of offerings like the Inference Engine and an AI‑Native Cloud. Larger $1M+ customer ARR also surged triple-digits, indicating product-driven expansion into higher-value use cases.
Profitability: The business is described as scaling profitably, posting strong net income and robust adjusted EBITDA margins while growing. Management commentary highlights continued profitable expansion even as investment in AI and capacity ramps.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.

We're building healthcare tech for a system that desperately needs it. Each year, millions of Americans deal with confusing changes to their Medicare plans that impact their prescriptions, access to care, and pocketbooks. These aren’t just inconveniences – they are potentially life-altering changes that leave seniors medically and financially vulnerable. Independent Medicare advisors play a crucial role in guiding seniors through this...

Spark Advisors's Top Stability & Growth Strengths
Market Expansion: Reported enrollments of roughly 250,000 in 2025 and a broker base exceeding 10,000 point to a rapidly widening operating footprint. AEP 2025 production metrics and tens of thousands of contracts processed further suggest the platform is scaling beyond its 2024 funding milestone.
Investor Backing & Capital Strength: A $25M Series B in January 2024, reportedly at a significant valuation step-up, underscores access to growth capital. Independent listings also record total funding in the high-$30Ms range, reinforcing external validation of capitalization.
Strong Hiring & Retention: Headcount reportedly expanded from around 40 to roughly 130 by 2025, and current postings include senior roles across revenue operations, engineering, product, and agent/customer experience. Active requisitions signal continued investment in growth infrastructure.



