

Top Security Companies in Denver & Boulder, CO (161)

Datadog (NASDAQ: DDOG) is a global SaaS business, delivering a rare combination of growth and profitability. We are on a mission to break down silos and solve complexity in the cloud age by enabling digital transformation, cloud migration, and infrastructure monitoring of our customers' entire technology stacks. Built by engineers, for engineers, Datadog is used by organizations of all sizes...

Datadog's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show accelerating top-line momentum, with FY2025 up 28% and Q2 2026 revenue up 36% year over year after 32% in Q1. Management also raised 2026 revenue guidance to $4.45B–$4.47B, indicating confidence in continued expansion.
Healthy Cash Flow: Cash generation is substantial, including Q2 2026 operating cash flow of $316M and free cash flow of $279M with about a 25% free-cash-flow margin. The company also reported roughly $5.0B in cash, cash equivalents and marketable securities as of June 30, 2026.
Customer Loyalty & Retention: Expansion within the installed base is a key driver, with about 75% of the 2025 revenue increase coming from existing customers and rising multi‑product adoption. Larger accounts are also expanding, as $100K+ ARR customers grew roughly 23% year over year to ~4,720 in Q2 2026.
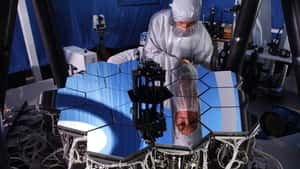
Improving the future and protecting lives is an ambitious mission, but it’s what we do. As a leading aerospace, defense, and security company, we work together to deliver a full range of products and services for air, land, space, and naval forces, as well as advanced electronics, security, information technology solutions and customer support services. How we work is rooted...
BAE Systems, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Sales increased 10% in 2025 and 9% in H1 2026, with leadership upgrading 2026 guidance to 8–10% sales growth. Growth was reported across all major sectors.
Profitability: Underlying EBIT rose 12% in 2025 and 11% in H1 2026, alongside an improved return on sales. This points to stronger margins in addition to top-line expansion.
Resilient & Sustainable Growth: A record order backlog of roughly £83.6–84.0 billion and multi‑year contracts provide substantial future revenue visibility. The 2026 outlook also signals continued expansion.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.
JumpCloud’s mission is to Make Work Happen®, providing simple, secure access to an organization’s technology resources from any device, or any location. The JumpCloud Open Directory Platform gives IT, security operations, and DevOps a single, cloud-based solution to control and manage employee identities and their devices, and apply conditional access controls based on Zero Trust principals. Since launching in 2012,...
JumpCloud's Top Stability & Growth Strengths
Market Expansion: Geographic reach has expanded from 100+ to 160+ countries, with infrastructure investment such as a new data center in India. These moves indicate continued international scaling rather than maintaining a static footprint.
Product Line Growth: The platform broadened beyond directory/identity to include PAM via VaultOne and identity-threat detection via Breez, alongside ongoing feature launches. This expansion into adjacent security categories suggests deliberate growth in addressable product scope.
Investor Backing & Capital Strength: The company has raised $400M+ to date and continues to undertake growth investments, including launching an investment arm focused on identity, security, AI, and IT productivity. This pattern points to sustained access to capital to support expansion.

Ockom provides advanced red team and pentesting capabilities to industry and government, as well as innovative compliance solutions and software.


ID Watchdog is the best identity theft protection and resolution system on the market. Developed with help from law enforcement authorities, judicial representatives, banks, and credit experts, our patent-pending technology searches thousands of databases to detect changes in the personal identity profiles of each of our members. Our unsurpassed resolution services allow for complete peace of mind.
Every day there’s another cyber-attack on the news. Hackers stole twenty million credit card numbers from a retailer, or they shut down an oil pipeline, or crippled a hospital. These attacks are more than just disruptive; they’re big business for organized crime and rogue states. Wiz is here to prevent them from happening where companies and governments build applications today...
Wiz's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Wiz is described as having secured substantial investments totaling roughly $1.9B, including a $1B round in May 2024 at a $12B valuation. The definitive agreement for an all-cash acquisition by Google for an estimated $32B is presented as major external validation of its scale and durability.
Strong Revenue Growth: Wiz is portrayed as scaling revenue quickly, including reaching $100M ARR within 18 months and reporting $350M ARR by 2023, with later references to ~$500M ARR by mid-2024. The company is also described as targeting $1B ARR, indicating continued growth expectations.
Strong Market Position & Advantage: Wiz is repeatedly characterized as a leader in cloud security/CNAPP, including being named a Leader in Forrester Wave evaluations and other industry recognitions. Its footprint among large enterprises is emphasized via statements about protecting a substantial share of Fortune 100 organizations and maintaining an agentless, API-centered platform differentiation.

Azorian Cyber Security Is a computer security firm based in Denver, Colorado with experience in penetration testing, compliance assessments, reputation management, incidence response,threat intelligence and computer forensics as well as being an innovator in the field of consumer cyber security. With over 15 years of experience in cyber security, secure design, testing and Ethical Hacking Azorian Cyber Security brings a multitude...

ADT is the most trusted brand in smart home and business security. Through innovative products, partnerships and the largest network of smart home security professionals in the United States, we connect and protect what matters most to our customers at home, work and on the go. For more information, visit www.adt.com.
ADT's Top Stability & Growth Strengths
Strong Market Position & Advantage: ADT is consistently described as the largest U.S. residential security monitoring provider and a leader in professionally monitored interactive systems. This scale and national footprint support resilience in recurring monitoring revenue.
Healthy Cash Flow: Recent results show meaningful growth in adjusted free cash flow with guidance for further improvement even as revenue stays roughly flat. Debt reduction and capital returns indicate strong cash generation from the core model.
Strategic Partnerships: Partnerships with Google and continued Nest integration enhance differentiation for pro install and monitoring and strengthen the ADT+ platform. These alliances expand ecosystem capabilities and distribution advantages.

At Pacific Office Automation (POA), we take pride in being a privately held office technology and managed services provider headquartered in Beaverton, Oregon. Since our founding in 1976 by Terry Newsom, we have grown from a small photocopier business into the largest independent office equipment dealer in the United States. Today, we generate approximately $491 million in annual revenue and...
Pacific Office Automation's Top Stability & Growth Strengths
Strong Revenue Growth: POA reported finishing 2025 above $507 million in revenue and cites 49 consecutive years of annual growth, with inclusion on regional fastest-growing lists reinforcing momentum.
Strong Market Position & Advantage: Multiple industry and OEM references describe POA as the largest independent U.S. office‑equipment dealer and a top-tier channel partner, with repeated Elite Dealer recognitions and OEM awards signaling standing.
Market Expansion: The company announced plans to enter four new cities in 2026 and executed acquisitions in April 2026 (Western Business Products and MKCnext), broadening its Western U.S. footprint and adding wide‑format capabilities.

Subsentio delivers affordable electronic surveillance solutions to service providers and law enforcement agencies. The company's solutions ΓÇô known as the Safe Harbor Probe, Harbor Intercept, and Harbor Master ΓÇô work for traditional telecommunications networks and broadband networks alike. And all three technical approaches are designed to conform to the industry-approved safe harbor technical standards adopted to comply with the CALEA...

Allegion (NYSE: ALLE) is a global pioneer in seamless access, with leading brands like CISA®, Interflex®, LCN®, Schlage®, SimonsVoss® and Von Duprin®. Focusing on security around the door and adjacent areas, Allegion secures people and assets with a range of solutions for homes, businesses, schools and institutions. Allegion had $2.7 billion in revenue in 2020, and its security products are...
Allegion's Top Stability & Growth Strengths
Strong Market Position & Advantage: Allegion is positioned as a leader in security products and access solutions, anchored by well-known brands and a strong competitive presence—particularly in its Americas business where pricing power and profitability are highlighted. Its scale, broad product coverage “around the door,” and continued relevance versus major competitors support resilience in core segments.
Profitability: Profitability appears strong, with expanding operating margins and rising adjusted EPS cited across 2024–2025 results. Consistent dividend increases also signal confidence in sustained earnings power and disciplined capital returns.
Healthy Cash Flow: Cash generation is described as robust, with available cash flow rising materially and funding dividends, buybacks, and acquisitions. Guidance also indicates continued strong cash conversion relative to earnings, supporting investment capacity and stability.

Code42 provides data loss protection, visibility, and recovery solutions. Code42 is not new to the cyber security scene — but our approach to insider risk protection is. For nearly 20 years, we’ve been safeguarding the data of more than 50,000 organizations, including 18 of the world’s most valuable brands. And as their needs — and the needs of their workforces —...
CipherPoint adds enterprise security features to Microsoft SharePoint and Google Docs with mass market pricing. The technology protects against loss or theft of healthcare records, credit card numbers, intellectual property, and other valuable data as a result of mistakes, outside attackers or rogue employees. The company is generating six figure revenues from direct sales and distribution partnerships, including a recent...

SP+ facilitates the efficient movement of people, vehicles and personal belongings with the goal of enhancing the consumer experience while improving bottom line results for our clients. The Company provides professional parking management, ground transportation, remote baggage check-in and handling, facility maintenance, security, event logistics, and other technology-driven mobility solutions to aviation, commercial, hospitality, healthcare and government clients across North...
We extract and analyzes data at scale from the darknet and provides tools for our customers to search, monitor and understand what is happening in the darknet. With the world’s largest database of darknet content, DarkOwl allows its customers—primarily other cybersecurity companies and law enforcement——to have “eyes on the darknet”.


StackHawk is a Series B software-as-a-service (SaaS) company that was founded in 2019. The company's mission is to empower developers to find, tirage, and fix application security bugs in CI/CD, before they hit production.


Founded in 2015, we help companies big and small alike manage and audit access to their databases, servers, clusters, and web applications.


ProtectWise is disrupting the security industry with The ProtectWise Grid™, delivering pervasive visibility, deep analytics and immersive visualization.


ManTech is more than a technology company. We are a company dedicated to service, and we consider our work a part of the public trust. The people of ManTech are privileged to work for the security of the United States, the welfare of our service members and veterans, the protection of our communities, and the cause of better health care. We...
ManTech's Top Stability & Growth Strengths
Strong Market Position & Advantage: ManTech is positioned as a credible leader within mission-focused federal cyber, intelligence support, and mission IT, supported by consistent placement in top federal contractor rankings and repeated wins on sizable national-security programs.
Market Expansion: Recent large awards across defense, intelligence, health, and civilian agencies (e.g., Air Force, DHA, NOAA, SOUTHCOM) indicate an expanding program footprint and broader participation across federal mission sets.
Investor Backing & Capital Strength: Private ownership under Carlyle is framed as enabling accelerated investment and an organic-plus-M&A value-creation approach, reinforcing capacity to fund capability build-outs.



