

Top Tech Companies in Denver & Boulder, CO (5,940)
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double-digit pace, with FY2025 up about 32% to $1.234B and Q1–Q2 2026 growing roughly 28% and 26% year over year, alongside raised FY2026 guidance implying around 24% growth. Larger-account cohorts also expanded materially, reinforcing the top-line trajectory.
Customer Loyalty & Retention: Dollar-based net revenue retention was approximately 109–110%, indicating existing customers are expanding spend on the platform. Higher-value segments grew quickly as well, including customers generating over $50K in ARR rising in the mid-to-high 30% range year over year.
Market Expansion: International revenue is outpacing overall growth, including 42% growth in FY2025 and mid-30% growth in early 2026. Total customers also surpassed 205,000 globally as enterprise and multi-product adoption broadened.
Block, Inc. is a global technology company with a focus on financial services. Made up of Square, Cash App, Afterpay, TIDAL, Bitkey, and Proto, Block, Inc. builds technology to increase access to the global economy. Each of our brands unlocks different aspects of the economy for more people. Square makes commerce and financial services accessible to sellers. Cash App is the...
Block's Top Stability & Growth Strengths
Profitability: Operating income has risen materially alongside growth, with the latest quarter reporting meaningful GAAP and adjusted operating profits and expanding margins. This indicates the business is scaling while improving earnings quality.
Resilient & Sustainable Growth: Gross profit is expanding at a strong, accelerating pace, with both Cash App and Square contributing and management raising full‑year outlooks. Longer‑term disclosures also highlight multi‑year compounding in gross profit per user across ecosystems.
Cost & Operational Efficiency: A leaner organizational structure and disciplined spending have driven record adjusted operating margins and improved operating leverage. Efficiency gains appear to be a second engine alongside revenue drivers.
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...
SRAM, LLC's Top Stability & Growth Strengths
Market Expansion: Facility build-outs in Portugal and new regional hubs in Italy, along with expansion in Taiwan and a Chicago HQ redevelopment, indicate a scaling global footprint. Company materials also cite 20+ locations across 10+ countries, underscoring broad geographic reach.
Product Line Growth: Recent launches such as RED AXS (2024) and Force AXS (2025), coupled with acquisitions including Ochain, Hammerhead, TIME, and Velocio, expand coverage across drivetrains, electronics, and accessories. This cadence points to continued investment in portfolio breadth.
Strong Market Position & Advantage: The company is repeatedly characterized as one of the world’s largest bicycle-component manufacturers and a primary rival to Shimano across premium segments. This standing reflects deep relevance with OEMs and the aftermarket.
Xero is small business accounting software that provides a platform on which businesses can build a fully integrated solution. It’s designed to make life better for people in small business, their advisors, and communities around the world. Xero minimises tedious admin by automating routine tasks, delivers valuable insights when needed, and brings together business data, trusted advisors, and powerful apps...
Xero's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show operating revenue rising at double‑digit rates across FY2025 and FY2026, with annualized recurring revenue increasing even faster. Growth is supported by both subscriber additions and higher average revenue per customer.
Healthy Cash Flow: Free cash flow increased year over year, indicating stronger cash generation alongside expansion. Reported figures highlight rising cash metrics even as the company scales investments.
Market Expansion: International revenue and subscribers continued to grow, with substantial gains outside Australia/New Zealand and ongoing progress in the U.S. aided by product and acquisition initiatives. Regional momentum in markets like the UK and North America underscores a widening footprint.
Moov is a payments infrastructure platform making it easy to accept, store, send, and spend money all from a single, elegantly-designed API. Instead of stitching together multiple vendors, software companies simply add Moov to their products to get the latest in payment technology, user onboarding, licensing, compliance, and more.
Moov's Top Stability & Growth Strengths
Product Line Growth: Current materials show support for accepting payments, bank payments, wallets, issuing cards, payouts, account verification, and multiple rails including ACH, RTP, and FedNow, positioning the company as infrastructure rather than only a card processor. This broader workflow coverage can increase payment volume per customer and create more acquisition opportunities.
Strategic Partnerships: Recent announcements and legal documents reference collaborations with institutions such as Jack Henry, Visa Direct, Coinbase, SouthState Bank, and Veridian Credit Union. These relationships extend distribution into community and regional financial institutions and reinforce enterprise readiness.
Investor Backing & Capital Strength: The funding trajectory progressed from a $5.5M seed and $27M Series A in 2020 to a $45M Series B in 2023 led by Commerce Ventures with participation from Andreessen Horowitz, Bain Capital Ventures, and Visa. This pattern signals sustained access to capital aligned with scaling the business and infrastructure.
Founded in 2015 by former NSA cyber operators, Huntress protects all businesses—not just the 1%—with enterprise-grade, fully owned and managed cybersecurity products at the price of an affordable SaaS application. The Huntress difference is our One Team advantage: our technology is designed with our industry-defining Security Operations Center (SOC) in mind and is never separated from our service. We protect...

Huntress's Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have risen from roughly $100M in 2024 to more than $250M by July 2026, with the company citing about 65–70% year-over-year growth across recent periods. Listings on Deloitte Technology Fast 500 and the Inc. 5000, tied to 543% three-year revenue growth, reinforce the high-growth trajectory.
Market Expansion: Geographic reach is described as extending to 100+ countries through distributor and reseller partnerships across EMEA, APAC, and Latin America. Protected businesses reportedly grew from 120,000+ in 2024 to 270,000+ by 2026, indicating broadening market penetration.
Product Line Growth: The platform has expanded beyond managed EDR into ITDR, Managed SIEM, security awareness training, and identity/endpoint posture management. Multiple launches following the 2024 Series D and integration of acquired security awareness capabilities point to a broader, multi-product offering.

Riot’s (NASDAQ: RIOT) vision is to be the world’s most trusted platform for powering and building digital infrastructure. Riot’s mission is to empower the future of digital infrastructure by positively impacting the sectors, networks, and communities that we touch. We believe that the combination of an innovative spirit and strong community partnership allows us to achieve best-in-class execution and create successful...

Riot Platforms, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding sharply, with full-year 2025 rising to $647.4M from $376.7M and Q2 2026 up 14% year over year. Growth also appeared in Q1 2026, indicating momentum beyond a single quarter.
Diversified Revenue Streams: A new data-center segment has begun contributing ($33.2M in Q1 2026; $23.2M in Q2 2026) alongside mining and engineering, indicating revenue is no longer tied solely to self-mining. AI/HPC-related activity broadens the mix beyond Bitcoin exposure.
Strategic Partnerships: Agreements with AMD (initial 25 MW delivered and option exercised to 50 MW) and a 20-year, 191 MW lease with a frontier AI lab provide multi-year contracted demand. These relationships help monetize a reported ~2.0 GW fully approved power pipeline.

Engine is the AI-native platform for intelligent travel. For a decade, Engine has built the proprietary technology and supply behind modern business travel, serving 40,000 customers and 2 million travelers, along with leading travel and AI companies that build on Engine's infrastructure. One system powers business travel, group travel, human agents, and AI agents. Engine has been recognized as one of...

Engine's Top Stability & Growth Strengths
Strong Revenue Growth: Reported roughly 70% year-over-year revenue growth in 2024 alongside expectations of 10M+ room nights points to strong top-line momentum. Independent press coverage corroborated these figures during the 2024 financing round.
Profitability: The company was described as profitable at scale around its 2024 funding milestone, indicating growth accompanied by operational discipline. Continued expansion into 2025–2026 has been paired with statements of cash-flow positivity.
Investor Backing & Capital Strength: A $140M Series C at a $2.1B valuation and a funding history totaling over $200M signal strong access to capital and investor confidence. The rising valuation from 2021 to 2024 underscores sustained financial backing.
Our Mission: Create a world where everyone has an authentic digital identity. Identity Digital is an internet infrastructure company that makes sure web addresses work seamlessly. If we do our job right, we are invisible to the user. We have the world’s largest portfolio of nearly 300 TLDs like .info, .pro, .world, which lets people and businesses build, market, and own...
Identity Digital's Top Stability & Growth Strengths
Strong Revenue Growth: Inclusion on the Inc. 5000 for five consecutive years and company statements of “healthy revenue growth” in 2025 indicate sustained top-line expansion. Three-year growth figures cited for recent periods (e.g., 152% then 82%) reinforce momentum, even though audited financials are not public.
Market Expansion: The .ai migration and subsequent surge (more than 60% YoY registrations in 2025, with registrar distribution roughly doubling) alongside multiple 2025 registry-agreement changes point to a growing footprint. Access to 1,800+ ICANN-accredited registrars and operations across 80+ locations further extend reach.
Strong Market Position & Advantage: Operating what is described as nearly 300 TLDs and supporting 28M+ domains, while resolving 60.4B+ DNS queries per day, signals substantial scale. Broad registrar access (including 90%+ coverage for .ai at migration) and a large installed base underscore competitive advantage.

Accuris gives engineers trusted answers, not just access. Our Engineering Intelligence platform combines verified data, actionable insights, and purpose-built workflows — so technical and business leaders can move faster, reduce risk, and make decisions they can defend.

Accuris's Top Stability & Growth Strengths
Strong Revenue Growth: Accuris reported it “substantially accelerated revenue growth” in 2024 and was on track to exceed its financial targets. It also described “exceptional momentum” in Q1 2025.
Product Line Growth: The company expanded its portfolio with Accuris Thread in 2025 and, in 2026, launched AI Assistant, BOM Intelligence, Change Impact Analysis, and a broader Engineering Intelligence platform. These moves indicate continued investment and expansion.
Market Expansion: Operational scale grew with a new Denver headquarters and offices in the UK, India, Malaysia, and Japan, alongside global headcount reaching 1,000+ across 20 countries. Accuris also reports 6,500+ organizations and 900,000 users, up from earlier disclosures.
We’re one of the world’s leading online gambling companies, revolutionizing the industry since 2000. Founded by Denise Coates CBE, we now employ over 10,000 people and serve over 120 million customers in 26 languages. We empower our employees to push boundaries and explore new ideas, cultivating a culture that celebrates and rewards creativity. This offers employees a wealth of...

bet365's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is on a clear upward trajectory, rising from about £3.72bn in FY2024 to roughly £4.04bn in FY2025, continuing multi‑year gains. The uplift builds on prior‑year growth and reflects momentum across the business.
Market Expansion: The company has broadened its geographic footprint with ongoing launches across North America (now live in numerous U.S. states plus Washington, D.C.) and new entries in Latin America. This expansion is cited as a contributor to top‑line growth and a focus on regulated markets.
Diversified Revenue Streams: Gaming revenue increased strongly while sports betting also grew, showing multiple engines driving the top line. This mix helped lift total revenue even as the business invested in new markets.
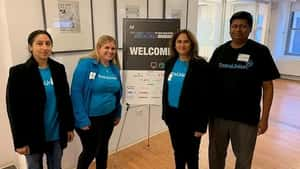
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is consistently climbing across 2025 and into 2026, with management increasing full‑year guidance after stronger‑than‑expected quarters. Momentum is led by U.S. Financial Services and Emerging Verticals, with multiple quarters of high single‑ to double‑digit organic growth noted.
Profitability: Net income and adjusted earnings expanded alongside revenue, and adjusted EBITDA also increased. This points to improving operating leverage as growth scales across key segments.
Diversified Revenue Streams: Multiple business lines—including credit, fraud/identity, marketing, and international operations—are contributing to results. Expansion such as taking majority ownership in the Mexico bureau and broad-based U.S. segment strength reduce reliance on any single product or geography.
Tune into the innovation, collaboration and culture that our team members bring to the office every day. We want you to be a part of our journey to build the next generation of technology that transforms the way the world communicates. Our team members are the key to our history of groundbreaking innovation and our continued progress. If you bring...

EchoStar's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted OIBDA increased to $493M in Q1 2026 from $400M in Q1 2025, and other recent periods show sizable OIBDA gains despite lower revenue. This pattern indicates tighter cost control and operational improvements.
Product Line Growth: Wireless service revenue rose in 2025 and again in Q2 2026, with ARPU up and multiple quarters previously showing net subscriber additions. These signals point to growth momentum within the wireless segment even as other lines contract.
Strong Market Position & Advantage: Hughes, an EchoStar company, was named a Leader in Gartner’s 2026 Magic Quadrant for Managed Network Services and has noted wins in aviation connectivity. Such recognition and enterprise traction support competitive strength in defined niches.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.
Mariner Wealth Advisors is a leading national wealth advisory firm. Mariner’s wealth advisory teams help clients achieve & maintain financial peace of mind – preserving the wealth they have created & building a legacy for future generations of family & business leaders. To do so, we provide holistic, innovative & client-focused solutions. We bring together talented resources, innovative offerings &...
Mariner Wealth Advisors's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Growth capital from institutional investors is positioned as fuel for ongoing acquisitions and platform build-out. Company communications through 2025–2026 continue to cite this partnership alongside active expansion.
Market Expansion: A steady cadence of acquisitions into 2026, coupled with a broad national office footprint, points to continued reach across markets. Early-2026 deals and ongoing pipeline updates indicate this lever remains central to growth.
Diversified Revenue Streams: The business spans private wealth, institutional consulting, and a supported-independence platform, with in-house tax, trust, and insurance capabilities. This multi-channel model suggests multiple sources of growth rather than reliance on a single line.
At monday.com, we help teams get more work done. We are the best AI work platform that empowers teams to automate, build, and scale their impact end-to-end with tools that actually execute the work for you. With over $1B in ARR, 250,000+ customers, and a global team, we’re serious about building a product people love to use and giving our...

monday.com's Top Stability & Growth Strengths
Profitability: Net income reached $118.7 million in 2025 versus $32.4 million in 2024 and a small loss in 2023, alongside record non‑GAAP operating income and margin improvements in 2026. This indicates the company is scaling efficiency while expanding.
Strong Revenue Growth: Revenue rose 27% in 2025 to $1.232 billion and continued to increase 22% year over year in Q2 2026, with management guiding 19%–20% growth for 2026. While the pace has moderated from earlier years, the top line remains firmly upward.
Innovation-Driven Growth: ARR from AI products doubled quarter over quarter in Q2 2026 and represented 17% of net new ARR. The pivot to an AI work platform is contributing discernible incremental demand.
Founded in 2013 in Hawaii and acquired by Booking Holdings in 2018, FareHarbor creates powerful tools that enable our clients (think boat rentals, museums, food tours, events and more!) to operate and grow. With over 20,000 clients across 90+ countries—we’re the largest in our industry and shaping the future of travel, together. Our team is an ‘Ohana of 900+...
FareHarbor's Top Stability & Growth Strengths
Market Expansion: Geographic reach and activity levels are growing, with 1,200+ operators joining from Australia and New Zealand and bookings in several major markets up 14% year over year. The operator base has risen from about 20,000 in 2024/25 to 23,000+ today, extending a long-run climb from roughly 5,000 at the 2018 acquisition.
Strategic Partnerships: Distribution reach has widened via the FareHarbor Distribution Network and deep integrations, including a global Booking.com tie-in that brings large volumes of attractions and OTA access. These connections drove a 27% year-over-year increase in total transaction volume in 2025 through partner and affiliate channels.
Product Line Growth: Product cadence remains high, with 184 platform updates in 2025 and further tools rolled out into 2026. This includes growth-focused offerings such as FareHarbor Sites and expanded distribution capabilities.
Apryse, previously known as PDFTron, takes document solutions to the next level, making work better and life simpler. As a global leader in document processing technology, Apryse gives developers, enterprise customers, and small businesses the tools they need to reach their document goals faster and easier. Apryse’s market-leading SDK drives digital transformation and powers next-generation software applications with dynamic document...
Apryse's Top Stability & Growth Strengths
Strong Revenue Growth: Reuters reporting indicates annual growth at a strong double-digit pace in 2025, aligning with sustained expansion activity. This growth is presented alongside ongoing platform and market advances from 2024–2026.
Profitability: EBITDA reportedly exceeded $100 million, indicating robust earnings capacity. This profile underpinned exploration of a multibillion-dollar sale process in 2025.
Product Line Growth: Acquisitions across 2024–2026 (e.g., LEAD Technologies, TallComponents, Scanbot SDK, Accusoft, PDF Tools AG) materially expanded capabilities in imaging, mobile capture, and high-performance PDF processing. Regular release cadences and AI-driven features further signal continued product expansion.
KPA solutions help clients identify, remedy, and prevent workplace safety and compliance problems across their entire enterprise. The combination of KPA’s easy-to-use software platforms, consulting services, and award-winning training content helps organizations minimize risk so they can focus on what’s important—their core business. For nearly 40 years, KPA has helped 10,000+ clients achieve regulatory compliance, protect their business, and keep...

KPA's Top Stability & Growth Strengths
Strong Market Position & Advantage: KPA is described as serving more than 15,000 businesses and cites relationships with 40 of the top 50 U.S. dealer groups, indicating deep penetration in its core automotive vertical. Its substantial customer footprint is repeatedly tied to a record year and ongoing expansion efforts.
Product Line Growth: The company reports an expanded product portfolio, including AI-powered compliance tools and enhancements like an updated Vera Suite dashboard. Announcements across 2025–2026 frame these launches as fueling accelerating innovation and growth.
Future-Ready Strategy: A 2026 reorganization refocused KPA on automotive, with leadership changes positioned to enable faster product development and deeper specialization. Continued partnerships and capability investments are presented as building for future growth.
DigitalOcean is the Inference Cloud — a full-stack, production-ready cloud platform built to run AI applications with predictable performance, sustainable economics, and radically simpler operations at scale. We are built for teams turning AI into real products — not just training models. Our advantage is not fewer features, but fewer failure modes when operating AI at scale — combining minimal...

DigitalOcean's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is reported up 29% year over year in Q2 2026 to $281M, with ARR at $1.125B also up 29%. Guidance for 2026 was raised to about 30–31% growth alongside record incremental ARR and a sharply higher RPO.
Innovation-Driven Growth: AI-related momentum is pronounced, with AI customer ARR at $234M, up about 212% year over year, and the launch of offerings like the Inference Engine and an AI‑Native Cloud. Larger $1M+ customer ARR also surged triple-digits, indicating product-driven expansion into higher-value use cases.
Profitability: The business is described as scaling profitably, posting strong net income and robust adjusted EBITDA margins while growing. Management commentary highlights continued profitable expansion even as investment in AI and capacity ramps.



