

Top Tech Companies in Denver & Boulder, CO (5,937)
Build what’s next — with tech that matters PwC provides professional services across Audit and Assurance, Advisory and Tax — powered by a global network of over 370,000 people in 149 countries. You may know us for our business expertise, but technology is core to how we help clients move faster, build trust and deliver meaningful outcomes. As a technologist, you’ll work...

PwC's Top Stability & Growth Strengths
Resilient & Sustainable Growth: Revenue has increased year over year to a new high, with all three major service lines posting gains despite a slower pace. Growth remains uneven by region, but the overall trajectory is upward over the last several fiscal years.
Future-Ready Strategy: Multi‑billion‑dollar investments in technology—especially nearly $1.5B in AI—along with acquisitions and scaling managed services indicate a deliberate pivot to future growth levers. Leadership attention to next‑generation audit and AI‑enabled capabilities underscores preparation for emerging demand.
Strong Market Position & Advantage: The organization is characterized as a leading global professional‑services network with broad scale across assurance, advisory, and tax and repeated external recognitions in select consulting categories. Reach across major multinational clients supports durable competitive positioning.
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with H1 2026 up 11% and Q1/Q2 growing 14% and 8% respectively, supported by higher commercial-aircraft deliveries. This momentum reflects increased production throughput and broader top-line recovery.
Healthy Cash Flow: Cash generation is improving, as H1 2026 operating cash flow turned positive and free cash flow improved, including a positive result in Q2. This shift indicates better working-capital dynamics alongside rising delivery volume.
Strong Market Position & Advantage: Backlog is at a record level of roughly $715 billion, including more than 6,200 commercial aircraft. This depth of contracted demand provides multi‑year visibility for production and revenue.
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...

SRAM, LLC's Top Stability & Growth Strengths
Market Expansion: Facility build-outs in Portugal and new regional hubs in Italy, along with expansion in Taiwan and a Chicago HQ redevelopment, indicate a scaling global footprint. Company materials also cite 20+ locations across 10+ countries, underscoring broad geographic reach.
Product Line Growth: Recent launches such as RED AXS (2024) and Force AXS (2025), coupled with acquisitions including Ochain, Hammerhead, TIME, and Velocio, expand coverage across drivetrains, electronics, and accessories. This cadence points to continued investment in portfolio breadth.
Strong Market Position & Advantage: The company is repeatedly characterized as one of the world’s largest bicycle-component manufacturers and a primary rival to Shimano across premium segments. This standing reflects deep relevance with OEMs and the aftermarket.
Wipfli is a leading national advisory and accounting firm with nearly 100 years of serving ambitious middle-market organizations. We understand our clients' unique challenges and help them succeed on their terms through assurance, tax, advisory, outsourcing and technology services. With 2,900+ associates and global alliances, we combine national capabilities with local relationships. "Wipfli" is the brand name under which Wipfli LLP...

Wipfli's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased across FY24–FY26 with consecutive year-over-year gains, indicating steady top-line momentum. Company disclosures describe this as “purposeful” and oriented toward sustainable long-term growth alongside expansion in advisory and technology.
Investor Backing & Capital Strength: A strategic minority investment from New Mountain Capital was secured to accelerate growth, fund technology and talent, and support acquisitions. This signals enhanced capital resources to pursue the firm’s expansion agenda.
Product Line Growth: Capabilities have broadened through acquisitions and internal investment, adding areas such as cybersecurity, privacy, risk, digital transformation, and technology services (e.g., CompliancePoint and Harbour Results transactions). New leadership roles focused on growth, sales, and corporate development reinforce the expanding services mix.
Welcome to Comcast. From the connectivity and platforms we provide to the content and experiences we create, we bring people together, globally. Our people think the world of our work, and that’s why our work is the best in the world.

Comcast's Top Stability & Growth Strengths
Healthy Cash Flow: Operating cash flow increased from $27.7 billion in 2024 to $33.6 billion in 2025, and Q2 2026 free cash flow was $4.6 billion, up 2.3% year over year. This indicates strong cash generation despite uneven top-line trends.
Diversified Revenue Streams: Connectivity revenue rose 4.2% to $46.0 billion in 2025 alongside growth in business services (to $10.2 billion), wireless lines (to 9.3 million), Peacock (revenue up 10% to $5.4 billion; paid subs up 22% to 44 million), and parks. Comcast also highlights six growth drivers—broadband, wireless, business services, studios, streaming, and parks—that represented about 60% of 2025 revenue.
Product Line Growth: Wireless and streaming scaled meaningfully, with approximately 1.5 million wireless line additions in 2025 and Peacock reaching 44 million paid subscribers that year and achieving first-time quarterly profitability in Q2 2026. Business services connectivity also expanded in 2026, including Q2 revenue up 3.7% and EBITDA up 5.0%.
Ibotta (NYSE: IBTA) is a leading performance marketing platform allowing brands to deliver digital promotions to over 200 million consumers through a network of publishers called the Ibotta Performance Network (IPN). The IPN allows marketers to influence what people buy, and where and how often they shop – all while paying only when their campaigns directly result in a sale....
Ibotta's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with major platforms and retailers are expanding distribution and activity. Feedback suggests Uber and Giant Eagle joined in 2026 and a multi‑year 7‑Eleven deal was announced, while relationships with Walmart, Instacart and DoorDash underpin third‑party publisher redemption revenue up 27% year over year in Q2 2026.
Market Expansion: Network usage is scaling across publishers and channels. Feedback suggests Q2 2026 redeemers rose 21% to 20.9M, third‑party publisher redemptions increased 27% year over year, and H1 2026 total redemptions climbed from 163.3M to 179.4M.
Strong Market Position & Advantage: Positioning reflects a leading role in U.S. digital promotions with privileged retailer access. Feedback suggests Walmart exclusivity, a network reaching 200M+ consumers, and 900+ clients representing 3,100+ CPG brands provide a defensible competitive footing.
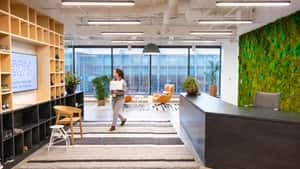
Gusto is a modern, online small business platform that helps small businesses take care of their teams. On top of full-service payroll, Gusto offers health insurance, 401(k)s, expert HR, and team management tools. Today, Gusto offices in Denver, San Francisco, and New York serve more than 400,000 businesses. Our customers come from all walks of life, and so do we. We...
Gusto's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reportedly surpassed $1 billion on a trailing-12-month basis, with management indicating growth accelerated across five consecutive quarters. A customer base exceeding 500,000 businesses underscores scale consistent with continued top-line expansion.
Healthy Cash Flow: The company is described as cash-flow positive for several years, indicating growth supported by operating discipline. This suggests expansion that is not overly dependent on external financing.
Product Line Growth: The acquisition of Guideline added retirement services to payroll/HR/benefits, and expansions into compliance, financial tools, and embedded capabilities broaden the offering. These additions create new monetization paths beyond core payroll.
_0.png)
Red 6 is an innovative Augmented Reality (AR) technology startup leading the way in synthetic air combat training. Our primary technology, supporting our ATARS product, enables pilots to simulate the cognitive challenges of flying while accessing realistic, scalable training in dynamic outdoor environments

Red 6's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Funding has progressed from a $30M Series A (2021) to a $70M Series B (2023), alongside a $30M AFWERX STRATFI award matched by $30M in private funding and subsequent 2026 financing. These capital infusions indicate substantial runway to scale technology integration and delivery.
Strategic Partnerships: Partnerships with Boeing, Lockheed Martin, Northrop Grumman, Leonardo, and Sierra Nevada Corporation are documented, including SNC’s role supporting a $30M multi-MAJCOM Air Force contract. Such alliances embed Red 6’s systems across multiple OEM and service ecosystems, reinforcing market access.
Market Expansion: Activity has advanced from demonstrations to integrations across platforms including T-38, F-16, MC-130J, Apache, and M-346, with traction spanning the U.S. Air Force, U.S. Navy, and allies like the RAF. Federal obligations and new awards (e.g., STRATFI, SBIR Phase III task orders) point to widening adoption.
For too long, child care programs have been stuck with clunky tools and manual processes, falling behind while other industries get all the high-tech toys. Playground is flipping the script. Playground is a proven platform for child care providers to streamline their operations, reclaim their time, and get back to the joy of teaching and caring. Our all-in-one child care management...

Playground (tryplayground.com)'s Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have doubled over the prior year and to be on track for at least another doubling, with profitability cited before the Series A. Hiring alongside revenue growth is described, reinforcing momentum.
Product Line Growth: The platform has expanded beyond basic communications into billing, payroll, enrollment, reporting, subsidy management, and AI tools such as Camber. Current product pages reflect a substantially broader offering than the original scope.
Market Expansion: The company states it serves 5,000+ childcare programs and 500,000+ owners, directors, teachers, and families across all 50 states, and a September 2026 acquisition by Procare underscores expanded reach within the category. Earlier usage metrics and ongoing hiring further illustrate scaling activity.

Hi. We’re Trustpilot. Trustpilot began in 2007 with a simple yet powerful idea that is more relevant today than ever — to be the universal symbol of trust, bringing consumers and businesses together through reviews. Trustpilot is open, independent, and impartial — we help consumers make the right choices and businesses to build trust, grow and improve. Today, we have more than 300...

Trustpilot's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue rose from $210.7M in 2024 to $261.1M in 2025 (+24% reported), with H1 2026 up 19% in constant currency to $151.4M. Consistent multi‑year increases and rising bookings (about +18% constant currency in FY2025 and H1 2026) indicate durable top‑line momentum.
Profitability: Adjusted EBITDA increased 69% to $40.7M in 2025 and rose 46% to $26.3M in H1 2026, expanding margins into the mid‑teens. Adjusted free cash flow also strengthened, reaching roughly $46.6M in 2025.
Market Expansion: North America is described as a fast‑growing region (bookings +27%), while enterprise traction accelerated (new logos +41% and >$20k customers compounding ~36% over three years). Platform scale expanded from 361M active reviews in 2025 to about 394M by mid‑2026, supporting broader commercial reach.

As the trusted choice for digital agencies, SaaS platforms, and web professionals, Duda powers over 1 million websites worldwide. Our platform offers a comprehensive suite of tools that enable users to efficiently create pixel-perfect, feature-rich websites at scale.

Duda, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Third-party estimates indicate revenue/ARR has risen meaningfully in recent cycles, with figures moving from roughly the mid-teens to the $40M–$75M range and directional growth reported from 2023 to 2025. Given the absence of audited disclosures, the clearest signal is the consistent upward trajectory rather than precise amounts.
Market Expansion: Company-reported adoption expanded from about 6,000 customers in 2019 to 23,000+ organizations, alongside growth from ~500,000 websites to 14M+ sites built and independent trackers detecting more active Duda domains. An agency- and partner-led go-to-market with hosts, media companies, and SaaS platforms underscores scaling distribution.
Innovation-Driven Growth: Rapid uptake of new AI capabilities (e.g., 45% of sites using at least one AI feature since 2023) and continued product expansion, including e-commerce via Snipcart and API-driven tooling, indicate product-led growth. Ongoing AI stack releases and professional workflows for agencies support deeper engagement and expansion.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.
Blissway is a transportation tech startup founded by Stanford grads that uses machine learning and IoT to simplify the collection of tolls and improve road safety. Backed by Y Combinator –the famed startup accelerator– and some of the best investors in Silicon Valley, we have been developing and testing our technology with the Colorado Department of Transportation and transportation agencies...

Blissway's Top Stability & Growth Strengths
Strong Hiring & Retention: Headcount and active hiring are described as increasing, with a new Denver headquarters and dedicated international recruiting indicating continued team expansion. Multiple profiles note ongoing engineering hires and growth in the 11–50 employee range.
Product Line Growth: The company’s offerings now span automated tolling, HOV/express-lane occupancy verification, commercial back-office systems, disaster-recovery/interim tolling, and point-to-point speed enforcement. This broader scope suggests movement from a single-solution focus toward a platform approach.
Market Expansion: Deployments in Colorado and inclusion in Washington State technology studies indicate activity beyond a single corridor, alongside the establishment of a Denver operational hub. References to statewide program use and corridor expansions point to a growing geographic footprint.

Riot’s (NASDAQ: RIOT) vision is to be the world’s most trusted platform for powering and building digital infrastructure. Riot’s mission is to empower the future of digital infrastructure by positively impacting the sectors, networks, and communities that we touch. We believe that the combination of an innovative spirit and strong community partnership allows us to achieve best-in-class execution and create successful...

Riot Platforms, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is expanding sharply, with full-year 2025 rising to $647.4M from $376.7M and Q2 2026 up 14% year over year. Growth also appeared in Q1 2026, indicating momentum beyond a single quarter.
Diversified Revenue Streams: A new data-center segment has begun contributing ($33.2M in Q1 2026; $23.2M in Q2 2026) alongside mining and engineering, indicating revenue is no longer tied solely to self-mining. AI/HPC-related activity broadens the mix beyond Bitcoin exposure.
Strategic Partnerships: Agreements with AMD (initial 25 MW delivered and option exercised to 50 MW) and a 20-year, 191 MW lease with a frontier AI lab provide multi-year contracted demand. These relationships help monetize a reported ~2.0 GW fully approved power pipeline.
We contribute to human progress by empowering people to express themselves, live in the moment, learn about the world, and have fun together.

Snap Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Revenue increased year over year in the latest quarters, with momentum accelerating into Q2 2026. Monetization per user improved, helping top-line growth outpace audience expansion.
Healthy Cash Flow: Adjusted EBITDA and free cash flow rose sharply, and the company generated positive free cash flow in the latest quarter. These gains indicate stronger operating leverage versus a year earlier.
Diversified Revenue Streams: Subscription and other direct-revenue products such as Snapchat+ expanded rapidly alongside core advertising. “Other revenue” grew significantly and the direct-revenue run rate scaled materially.
A global leader in applied safety science, UL Solutions transforms safety, security and sustainability challenges into opportunities for customers in more than 100 countries. UL Solutions delivers testing, inspection and certification services, together with software products and advisory offerings, that support our customers’ product innovation and business growth. The UL Certification Marks serve as a recognized symbol of trust in...

UL Solutions's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue has increased for multiple consecutive years, surpassing $3.0B in 2025 with continued growth into early 2026, including positive organic gains across all major segments. Filings indicate the trajectory is broad-based rather than acquisition-driven.
Profitability: Profitability is expanding faster than sales, with strong adjusted EBITDA growth and notable margin improvement in 2025. Subsequent quarterly updates show further gains, reinforcing operating leverage.
Healthy Cash Flow: Operating cash flow increased to roughly $600M in 2025, with stronger free cash flow supporting continued investment in labs and capacity expansion. This cash generation underpins ongoing growth initiatives.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is consistently climbing across 2025 and into 2026, with management increasing full‑year guidance after stronger‑than‑expected quarters. Momentum is led by U.S. Financial Services and Emerging Verticals, with multiple quarters of high single‑ to double‑digit organic growth noted.
Profitability: Net income and adjusted earnings expanded alongside revenue, and adjusted EBITDA also increased. This points to improving operating leverage as growth scales across key segments.
Diversified Revenue Streams: Multiple business lines—including credit, fraud/identity, marketing, and international operations—are contributing to results. Expansion such as taking majority ownership in the Mexico bureau and broad-based U.S. segment strength reduce reliance on any single product or geography.
We built AirDNA to solve a problem: how do you make smart short-term rental decisions when there’s too much guesswork and not enough good data? What started in a garage in California in 2015 is now a global team helping thousands of people — from aspiring hosts to major real estate firms — make confident choices about where to invest, what...

AirDNA's Top Stability & Growth Strengths
Product Line Growth: The product footprint has broadened with additions like Booking.com data, for‑sale property data, and newer tools that extend use cases from analytics into operations. Capability expansion is also evident via acquisitions such as Arrivalist and Uplisting.
Market Expansion: Data coverage now spans millions of listings across 120,000+ markets and all three major OTAs, indicating wider geographic and channel reach. Large reported user and customer counts across investors, hosts, managers, and public agencies reinforce this breadth.
Investor Backing & Capital Strength: Alpine Investors’ 2022 investment and subsequent M&A support suggest solid access to capital to scale products and go‑to‑market. Leadership messaging frames the company as entering its “next phase of growth” under this backing.
We’re one of the world’s leading online gambling companies, revolutionizing the industry since 2000. Founded by Denise Coates CBE, we now employ over 10,000 people and serve over 120 million customers in 26 languages. We empower our employees to push boundaries and explore new ideas, cultivating a culture that celebrates and rewards creativity. This offers employees a wealth of...

bet365's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is on a clear upward trajectory, rising from about £3.72bn in FY2024 to roughly £4.04bn in FY2025, continuing multi‑year gains. The uplift builds on prior‑year growth and reflects momentum across the business.
Market Expansion: The company has broadened its geographic footprint with ongoing launches across North America (now live in numerous U.S. states plus Washington, D.C.) and new entries in Latin America. This expansion is cited as a contributor to top‑line growth and a focus on regulated markets.
Diversified Revenue Streams: Gaming revenue increased strongly while sports betting also grew, showing multiple engines driving the top line. This mix helped lift total revenue even as the business invested in new markets.
We're a global community of bold visionaries and resourceful doers who are shaping the future of Dropbox—and with it the future of work. Our Virtual First model combines the flexibility of a distributed workplace with the power of human connection, making space for both meaningful work and meaningful relationships. With our start-up mindset and enterprise-level opportunities, you can be who...

Dropbox's Top Stability & Growth Strengths
Profitability: Profitability is depicted as strong, with non-GAAP operating margins near 40% and improved GAAP net income. Feedback suggests this strength persists even amid slow top-line growth.
Healthy Cash Flow: Cash generation is highlighted as substantial, including FY2025 free cash flow above $1B and significant unlevered free cash flow in Q2 2026. Feedback suggests robust cash flow supports buybacks and financial flexibility.
Resilient & Sustainable Growth: Core operations are portrayed as stabilizing in 2026 with low single-digit revenue and ARR growth excluding FormSwift. Feedback suggests paying users have resumed modest sequential increases, indicating resilience.



