

Top Tech Companies in Denver & Boulder, CO (5,934)
A leading global aerospace company and top U.S. exporter, Boeing develops, manufactures and services commercial airplanes, defense products and space systems for customers in more than 150 countries. Our U.S. and global workforce and supplier base drive innovation, economic opportunity, sustainability and community impact. Boeing is committed to fostering a culture based on our core values of safety, quality and...

Boeing's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising year over year, with H1 2026 up 11% and Q1/Q2 growing 14% and 8% respectively, supported by higher commercial-aircraft deliveries. This momentum reflects increased production throughput and broader top-line recovery.
Healthy Cash Flow: Cash generation is improving, as H1 2026 operating cash flow turned positive and free cash flow improved, including a positive result in Q2. This shift indicates better working-capital dynamics alongside rising delivery volume.
Strong Market Position & Advantage: Backlog is at a record level of roughly $715 billion, including more than 6,200 commercial aircraft. This depth of contracted demand provides multi‑year visibility for production and revenue.
Founded in Chicago in 1987 by Stan Day, SRAM, LLC has grown to be one of the world's largest bicycle component manufacturers. Today, we are led by CEO, Ken Lousberg, and Stan Day serves as Chairman of our Board. SRAM’s global footprint helps us bring cycling to every corner of the globe, including your local roads and trails. We design and...

SRAM, LLC's Top Stability & Growth Strengths
Market Expansion: Facility build-outs in Portugal and new regional hubs in Italy, along with expansion in Taiwan and a Chicago HQ redevelopment, indicate a scaling global footprint. Company materials also cite 20+ locations across 10+ countries, underscoring broad geographic reach.
Product Line Growth: Recent launches such as RED AXS (2024) and Force AXS (2025), coupled with acquisitions including Ochain, Hammerhead, TIME, and Velocio, expand coverage across drivetrains, electronics, and accessories. This cadence points to continued investment in portfolio breadth.
Strong Market Position & Advantage: The company is repeatedly characterized as one of the world’s largest bicycle-component manufacturers and a primary rival to Shimano across premium segments. This standing reflects deep relevance with OEMs and the aftermarket.
Skillsoft (NYSE: SKIL) is a global leader in AI-native skills management for the human + AI era. By unifying learning, real-time skills intelligence, and workforce insights, Skillsoft helps enterprises build their Skillforce™ — humans and AI working together to drive measurable business outcomes. Through personalized, interactive learning across leadership, technology, and compliance, Skillsoft enables organizations to close critical skill gaps...

Skillsoft's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted EBITDA held roughly stable to slightly higher year over year and free cash flow improved in the latest periods, indicating tighter operations despite softer sales. Management focus on efficiency helped margins while the business pivots toward subscriptions and AI.
Innovation-Driven Growth: A next‑generation AI‑native Percipio platform is in market with new customers, and usage of AI capabilities (including CAISY and related tools) is rising among early adopters. These signals point to product‑led momentum within the core enterprise offering even as consolidated revenue declines.
Customer Loyalty & Retention: Enterprise subscription revenue has been comparatively resilient across recent years, with indicators like improved dollar retention and steady TDS performance suggesting stable customer relationships. Professional‑services revenue also increased, reinforcing ongoing engagement with enterprise accounts.
.png)
We bridge deep tech into farming and ranching. Halter enables farmers and ranchers to remotely shift, virtually fence and proactively monitor their cows’ health and behavior. Can you imagine watching 500 cows or cattle walk calmly towards the milking shed or their next break? No quad bikes, no dogs, no fences. Just a herd of cows walking at their own...

Halter's Top Stability & Growth Strengths
Market Expansion: Geographic reach is widening quickly, with operations scaling across many U.S. states and stated plans to enter the U.K. and Ireland alongside continued growth in New Zealand and Australia. Customer adoption also broadened materially, with notable increases in the number of ranches and farms using the platform.
Investor Backing & Capital Strength: Capital access strengthened through sizable late‑stage rounds at markedly higher valuations within a short span, with independent confirmations of the most recent raise. This trajectory indicates strong investor confidence to fund continued commercial and product expansion.
Strong Revenue Growth: New Zealand filings and reporting indicate materially higher subscription and segment revenues over recent periods. These financial signals align with increased collar deployments and a larger installed base.
.png)
Klaviyo (NYSE: KVYO) is the B2C CRM. Powered by its built-in data platform and AI, Klaviyo combines marketing automation, analytics, and customer service into one unified solution, making it easy for businesses to know their customers and grow faster. Klaviyo (CLAY-vee-oh) helps over 183,000 brands like Mattel, Glossier, Daily Harvest, and Liquid Death deliver 1:1 experiences at scale, improve efficiency,...
Klaviyo's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is rising at a double-digit pace, with FY2025 up about 32% to $1.234B and Q1–Q2 2026 growing roughly 28% and 26% year over year, alongside raised FY2026 guidance implying around 24% growth. Larger-account cohorts also expanded materially, reinforcing the top-line trajectory.
Customer Loyalty & Retention: Dollar-based net revenue retention was approximately 109–110%, indicating existing customers are expanding spend on the platform. Higher-value segments grew quickly as well, including customers generating over $50K in ARR rising in the mid-to-high 30% range year over year.
Market Expansion: International revenue is outpacing overall growth, including 42% growth in FY2025 and mid-30% growth in early 2026. Total customers also surpassed 205,000 globally as enterprise and multi-product adoption broadened.
For too long, child care programs have been stuck with clunky tools and manual processes, falling behind while other industries get all the high-tech toys. Playground is flipping the script. Playground is a proven platform for child care providers to streamline their operations, reclaim their time, and get back to the joy of teaching and caring. Our all-in-one child care management...

Playground (tryplayground.com)'s Top Stability & Growth Strengths
Strong Revenue Growth: ARR is reported to have doubled over the prior year and to be on track for at least another doubling, with profitability cited before the Series A. Hiring alongside revenue growth is described, reinforcing momentum.
Product Line Growth: The platform has expanded beyond basic communications into billing, payroll, enrollment, reporting, subsidy management, and AI tools such as Camber. Current product pages reflect a substantially broader offering than the original scope.
Market Expansion: The company states it serves 5,000+ childcare programs and 500,000+ owners, directors, teachers, and families across all 50 states, and a September 2026 acquisition by Procare underscores expanded reach within the category. Earlier usage metrics and ongoing hiring further illustrate scaling activity.

As the trusted choice for digital agencies, SaaS platforms, and web professionals, Duda powers over 1 million websites worldwide. Our platform offers a comprehensive suite of tools that enable users to efficiently create pixel-perfect, feature-rich websites at scale.

Duda, Inc.'s Top Stability & Growth Strengths
Strong Revenue Growth: Third-party estimates indicate revenue/ARR has risen meaningfully in recent cycles, with figures moving from roughly the mid-teens to the $40M–$75M range and directional growth reported from 2023 to 2025. Given the absence of audited disclosures, the clearest signal is the consistent upward trajectory rather than precise amounts.
Market Expansion: Company-reported adoption expanded from about 6,000 customers in 2019 to 23,000+ organizations, alongside growth from ~500,000 websites to 14M+ sites built and independent trackers detecting more active Duda domains. An agency- and partner-led go-to-market with hosts, media companies, and SaaS platforms underscores scaling distribution.
Innovation-Driven Growth: Rapid uptake of new AI capabilities (e.g., 45% of sites using at least one AI feature since 2023) and continued product expansion, including e-commerce via Snipcart and API-driven tooling, indicate product-led growth. Ongoing AI stack releases and professional workflows for agencies support deeper engagement and expansion.
Gusto is a modern, online small business platform that helps small businesses take care of their teams. On top of full-service payroll, Gusto offers health insurance, 401(k)s, expert HR, and team management tools. Today, Gusto offices in Denver, San Francisco, and New York serve more than 400,000 businesses. Our customers come from all walks of life, and so do we. We...
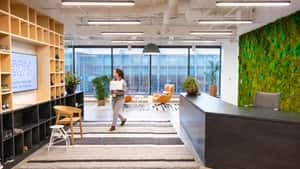
Gusto's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue reportedly surpassed $1 billion on a trailing-12-month basis, with management indicating growth accelerated across five consecutive quarters. A customer base exceeding 500,000 businesses underscores scale consistent with continued top-line expansion.
Healthy Cash Flow: The company is described as cash-flow positive for several years, indicating growth supported by operating discipline. This suggests expansion that is not overly dependent on external financing.
Product Line Growth: The acquisition of Guideline added retirement services to payroll/HR/benefits, and expansions into compliance, financial tools, and embedded capabilities broaden the offering. These additions create new monetization paths beyond core payroll.

We’re powering a better social safety net. Building healthier and happier communities starts with supporting the whole person. That’s why Findhelp was founded in 2010: to connect all people in need to the programs that serve them with dignity and ease. Our software platform enables community organizations, governments, and businesses across industries to easily manage and coordinate care. From screening and...

Findhelp's Top Stability & Growth Strengths
Investor Backing & Capital Strength: A major 2026 investment of approximately $250 million from TPG’s Rise Fund is presented as fuel to scale the platform, expand the national network, and invest in technology. This level of capital support signals capacity to pursue multi-state implementations and product acceleration.
Market Expansion: Customer counts are reported to have risen from 570+ in 2023 to 825+ across all 50 states alongside new statewide wins in New Mexico and New York. Additional public-sector rollouts (e.g., TennCare and Delaware) and millions of monthly searches point to broader geographic and institutional reach.
Product Line Growth: Acquisitions such as Uno Health (2025) and Kiip (2024) expand capabilities from referrals toward digital eligibility, enrollment, and case management. This broadened scope supports a shift toward a more complete, full-stack social-care platform.

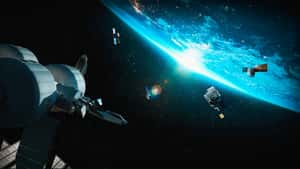
Securing The Freedom of Operations Headquartered in Colorado, Sierra Space is a mission-proven Defense Tech company delivering satellite platforms, critical subsystems, reusable spaceplanes, hypersonic technologies, propulsion systems, and infrastructure for the nation’s most critical missions. With more than three decades of heritage and a record of flight-proven success in space, Sierra Space is trusted by U.S. National Security, Civil customers, and global...
Sierra Space's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has grown markedly, including a $550 million Series C in March 2026 that lifted total investments since 2021 above $2 billion and valued the company at $8 billion. This financing momentum aligns with sizable government awards and ongoing scale-up efforts.
Market Expansion: The creation of a dedicated defense unit, new manufacturing capacity (e.g., the 60,000-square-foot Victory Works) and a footprint exceeding 1 million square feet indicate expansion from development into larger-scale defense manufacturing. Significant awards since 2023—such as $1.5 billion in defense contracts and Space Development Agency awards of $740 million (2024) and $798 million (2026)—reinforce this broader market reach.
Diversified Customer Base: Activity spans national-security customers, NASA (e.g., a lunar logistics study and payloads for the Dream Chaser inaugural flight), the U.S. Air Force (engine development), and Mitsubishi Heavy Industries (ISS docking components). This mix points to multiple civil, defense, commercial, and international demand sources.

At monday.com, we help teams get more work done. We are the best AI work platform that empowers teams to automate, build, and scale their impact end-to-end with tools that actually execute the work for you. With over $1B in ARR, 250,000+ customers, and a global team, we’re serious about building a product people love to use and giving our...

monday.com's Top Stability & Growth Strengths
Profitability: Net income reached $118.7 million in 2025 versus $32.4 million in 2024 and a small loss in 2023, alongside record non‑GAAP operating income and margin improvements in 2026. This indicates the company is scaling efficiency while expanding.
Strong Revenue Growth: Revenue rose 27% in 2025 to $1.232 billion and continued to increase 22% year over year in Q2 2026, with management guiding 19%–20% growth for 2026. While the pace has moderated from earlier years, the top line remains firmly upward.
Innovation-Driven Growth: ARR from AI products doubled quarter over quarter in Q2 2026 and represented 17% of net new ARR. The pivot to an AI work platform is contributing discernible incremental demand.
Cloudflare, Inc. (NYSE: NET) is the leading connectivity cloud company on a mission to help build a better Internet. It empowers organizations to make their employees, applications and networks faster and more secure everywhere, while reducing complexity and cost. Cloudflare’s connectivity cloud delivers the most full-featured, unified platform of cloud-native products and developer tools, so any organization can gain the...

Cloudflare's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results show revenue rising in the mid-30% year over year, with acceleration from Q1 to Q2 2026 and raised full-year 2026 guidance. Contracted demand indicators such as Current RPO also increased in the mid-30% range, reinforcing momentum.
Diversified Customer Base: Evidence points to a broad customer mix, from hundreds of thousands of paying customers to thousands of large enterprises, including a significant share of the Fortune 500. Growth in $100K+ and $1M+ spend cohorts underscores continued upmarket penetration.
Healthy Cash Flow: Observations include positive and increasing free cash flow alongside strong operating cash generation in recent periods. These trends suggest the business is funding growth while improving cash efficiency.
Mariner Wealth Advisors is a leading national wealth advisory firm. Mariner’s wealth advisory teams help clients achieve & maintain financial peace of mind – preserving the wealth they have created & building a legacy for future generations of family & business leaders. To do so, we provide holistic, innovative & client-focused solutions. We bring together talented resources, innovative offerings &...
Mariner Wealth Advisors's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Growth capital from institutional investors is positioned as fuel for ongoing acquisitions and platform build-out. Company communications through 2025–2026 continue to cite this partnership alongside active expansion.
Market Expansion: A steady cadence of acquisitions into 2026, coupled with a broad national office footprint, points to continued reach across markets. Early-2026 deals and ongoing pipeline updates indicate this lever remains central to growth.
Diversified Revenue Streams: The business spans private wealth, institutional consulting, and a supported-independence platform, with in-house tax, trust, and insurance capabilities. This multi-channel model suggests multiple sources of growth rather than reliance on a single line.
.png)
Since we opened our doors in 2009, the world of commerce has evolved immensely, and so has Square. After enabling anyone to take payments and never miss a sale, we saw sellers stymied by disparate, outmoded products and tools that wouldn’t work together. So we expanded into software and started building integrated, omnichannel solutions – to help sellers sell online, manage...

Square's Top Stability & Growth Strengths
Profitability: Square gross profit increased year over year in 2025 and again in recent quarters, with gains driven by processing, software, and financial solutions like Square Loans. Filings indicate this momentum continued into 2026, with growth excluding hardware also improving.
Strong Market Position & Advantage: Square is described as a leader in small-business POS and commerce, serving millions of sellers and processing a very large volume of payments. Industry recognition and scale suggest durable competitive positioning in its core segments.
Market Expansion: International payment volume is growing faster than the U.S., and sectors such as food and beverage led recent gains. Seller acquisition accelerated late in 2025, indicating widening reach across geographies and customer segments.
TransUnion is a global information and insights company that makes trust possible by ensuring that each consumer is reliably and safely represented in the marketplace. We do this by having an accurate and comprehensive picture of each person. This picture is grounded in our legacy as a credit reporting agency which enables us to tap into both credit and public record...
TransUnion's Top Stability & Growth Strengths
Strong Revenue Growth: Revenue is consistently climbing across 2025 and into 2026, with management increasing full‑year guidance after stronger‑than‑expected quarters. Momentum is led by U.S. Financial Services and Emerging Verticals, with multiple quarters of high single‑ to double‑digit organic growth noted.
Profitability: Net income and adjusted earnings expanded alongside revenue, and adjusted EBITDA also increased. This points to improving operating leverage as growth scales across key segments.
Diversified Revenue Streams: Multiple business lines—including credit, fraud/identity, marketing, and international operations—are contributing to results. Expansion such as taking majority ownership in the Mexico bureau and broad-based U.S. segment strength reduce reliance on any single product or geography.

Space was once the quietest place in the universe. Now, it's crowded, contested, and confrontational. We are True Anomaly: the only defense company focused exclusively on space defense. Founded in 2022 by ex-U.S. Space Force members, True Anomaly designs and builds advanced systems for space superiority: agile and powerful spacecraft platforms, mission software engineered for unmatched command and control, and payloads...

True Anomaly's Top Stability & Growth Strengths
Investor Backing & Capital Strength: Capital raised has accelerated from a $260M Series C in 2025 to a $650M Series D in 2026, pushing cumulative funding above $1B and indicating substantial financing capacity. Funding is described as enabling facility expansion, manufacturing scale-up, and a larger mission cadence.
Strong Hiring & Retention: Headcount expanded from a small founding team to ~250 by end-2025, with stated targets of 500+ in 2026 and 1,000+ in 2028 alongside multi-site growth in Colorado and Long Beach. Independent coverage during 2026 also points to 250–300+ employees, reinforcing tangible workforce scaling.
Strong Market Position & Advantage: Selection for multiple Space Force efforts—such as VICTUS HAZE operations, Kronos software, GHOST-R/RG-XX, and Space-Based Interceptors—signals movement from small R&D awards toward larger defense procurement. The company reports transition from development flights to operational missions, including a space-to-space pursuit during VICTUS HAZE.
.jpeg)
We are a world leader in innovative memory solutions that transform how the world uses information to enrich life for all. For over 45 years, our company has been instrumental to the world’s most significant technology advancements, delivering optimal memory and storage systems for a broad range of applications.

Micron Technology's Top Stability & Growth Strengths
Strong Revenue Growth: Recent results indicate a sharp acceleration in sales, with quarterly revenue several times higher than a year earlier and sequential gains continuing. Management guidance suggests this momentum is expected to carry into the next quarter.
Profitability: Margins and net income have expanded dramatically alongside stronger pricing and mix toward AI-related products. Operating cash generation has also risen substantially, reinforcing financial strength.
Innovation-Driven Growth: Advanced AI memory offerings—such as HBM, high-capacity DIMMs, and server DRAM—are described as ramping rapidly and contributing materially to the top line. Segment data shows broad gains in cloud, core data center, mobile/client, and automotive/embedded tied to these innovations.
Inspira Financial provides health, wealth, retirement, and benefits solutions that strengthen and simplify the health and wealth journey. With more than 7 million clients, representing over $62 billion in assets, Inspira works with thousands of employers, plan sponsors, recordkeepers, TPAs, and other institutional partners — helping the people they care about plan, save, and invest for a brighter future. Inspira...

Inspira Financial's Top Stability & Growth Strengths
Market Expansion: Distribution channels are broadening through announced arrangements with Ameritas and an integration with CAIS, extending reach into retirement platforms and advisor access to alternatives. Company materials also cite support for more than 150,000 employers, indicating efforts to expand reach beyond the existing base.
Product Line Growth: Acquisitions such as NuView and First Dollar, along with the addition of Quest Trust’s self-directed IRA business, expanded capabilities across retirement, benefits technology, and alternative-asset custody. The offering now spans health, wealth, retirement, and consumer-directed benefits, signaling a wider solution set.
Strategic Partnerships: Relationships include the majority of the 10 largest U.S. retirement-plan recordkeepers and a broad employer network, anchoring institutional distribution. New integrations like CAIS further embed the platform within advisor and recordkeeper ecosystems.
Ibotta (NYSE: IBTA) is a leading performance marketing platform allowing brands to deliver digital promotions to over 200 million consumers through a network of publishers called the Ibotta Performance Network (IPN). The IPN allows marketers to influence what people buy, and where and how often they shop – all while paying only when their campaigns directly result in a sale....
Ibotta's Top Stability & Growth Strengths
Strategic Partnerships: Partnerships with major platforms and retailers are expanding distribution and activity. Feedback suggests Uber and Giant Eagle joined in 2026 and a multi‑year 7‑Eleven deal was announced, while relationships with Walmart, Instacart and DoorDash underpin third‑party publisher redemption revenue up 27% year over year in Q2 2026.
Market Expansion: Network usage is scaling across publishers and channels. Feedback suggests Q2 2026 redeemers rose 21% to 20.9M, third‑party publisher redemptions increased 27% year over year, and H1 2026 total redemptions climbed from 163.3M to 179.4M.
Strong Market Position & Advantage: Positioning reflects a leading role in U.S. digital promotions with privileged retailer access. Feedback suggests Walmart exclusivity, a network reaching 200M+ consumers, and 900+ clients representing 3,100+ CPG brands provide a defensible competitive footing.

Tune into the innovation, collaboration and culture that our team members bring to the office every day. We want you to be a part of our journey to build the next generation of technology that transforms the way the world communicates. Our team members are the key to our history of groundbreaking innovation and our continued progress. If you bring...

EchoStar's Top Stability & Growth Strengths
Cost & Operational Efficiency: Adjusted OIBDA increased to $493M in Q1 2026 from $400M in Q1 2025, and other recent periods show sizable OIBDA gains despite lower revenue. This pattern indicates tighter cost control and operational improvements.
Product Line Growth: Wireless service revenue rose in 2025 and again in Q2 2026, with ARPU up and multiple quarters previously showing net subscriber additions. These signals point to growth momentum within the wireless segment even as other lines contract.
Strong Market Position & Advantage: Hughes, an EchoStar company, was named a Leader in Gartner’s 2026 Magic Quadrant for Managed Network Services and has noted wins in aviation connectivity. Such recognition and enterprise traction support competitive strength in defined niches.



